
Equipment financing · construction
Construction Equipment Financing: Excavators, Skid Steers, Loaders and More
Heavy equipment holds its value, which is why it finances well even for newer contractors and B/C credit. Here is what contractors finance, the terms lenders offer in 2026, how used and auction purchases work, and how to time a purchase for Section 179.
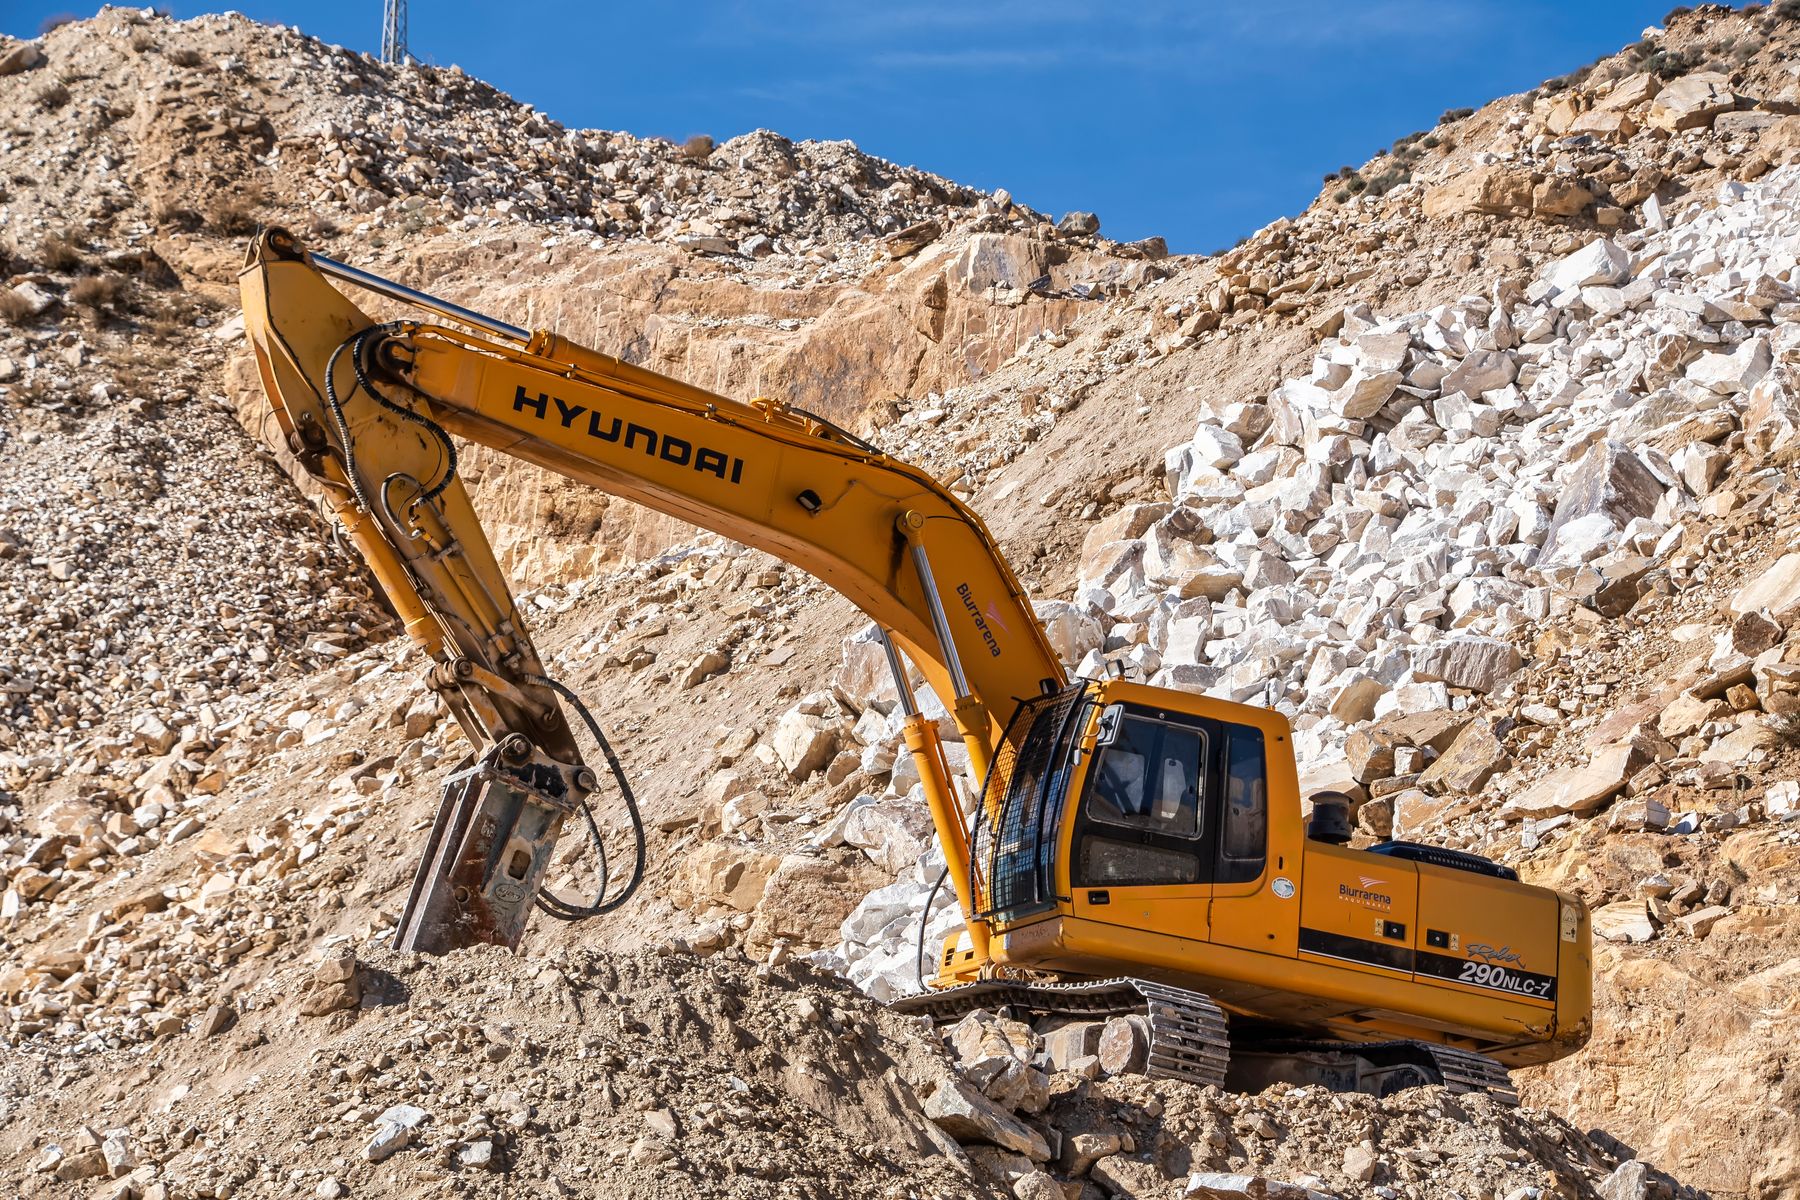
How Does Construction Equipment Financing Work?
Construction equipment is financed with an equipment loan or lease secured by the machine. Through our lender network, deals run from $15,000 to $3 million, terms of 36 to 84 months, up to 100% of the invoice for established contractors (10–20% down on used, auction and B/C deals), and rates from about 7% to 16% for most profiles. Used equipment up to 10–15 years old is routinely financed, including auction and private-party purchases with an inspection. App-only approvals go to $300,000, so a $250,000 excavator can be approved on bank statements in hours.
What Construction Businesses Finance
| Equipment | Typical cost | Typical term |
|---|---|---|
| Mini excavator | $40,000–$90,000 | 36–60 months |
| Full-size excavator | $150,000–$450,000 | 48–84 months |
| Skid steer / compact track loader | $40,000–$100,000 | 36–60 months |
| Wheel loader / backhoe | $80,000–$250,000 | 48–72 months |
| Dozer / grader | $150,000–$500,000 | 48–84 months |
| Dump truck / water truck | $80,000–$250,000 | 48–72 months |
| Paving / compaction | $50,000–$400,000 | 48–72 months |
| Cranes, boom lifts, telehandlers | $60,000–$600,000 | 48–84 months |
| Attachments and tools | $5,000–$50,000 | 24–48 months |
Attachments can usually be financed with the host machine on one agreement.
Programs and Terms for Construction
| Typical | |
|---|---|
| Deal size | $15,000–$3,000,000 |
| Term | 36–84 months |
| Down payment | 0–10% established contractors; 10–20% used, auction, B/C credit |
| Credit | 620+ standard; 550+ asset-based |
| Time in business | 1+ year; start-ups with trade experience and 15–25% down |
| App-only limit | Up to $300,000 |
| Speed | 2–5 business days; add 3–7 for private-party inspections |
Heavy equipment is the strongest collateral class after titled trucks: auction values are transparent and the machines last. Lenders stretch terms and credit accordingly.
Monthly payment on a $200,000 excavator, 60 months
Illustrative. A machine billing $8,000–$12,000 a month on jobs covers any of these.
How Lenders Look at Construction Deals
- The machine: make, model, year, hours, condition; mainstream brands (Cat, Deere, Komatsu, Kubota, Bobcat, Case, Volvo) price best.
- The contractor: time in business, license, bonding, backlog and signed contracts for newer firms.
- Cash flow: bank statements; lenders look for deposits that cover the payment after existing equipment notes.
- Existing equipment debt: a contractor with six notes is fine if each is current and the fleet is working.
- Private sales and auctions: financed with a bill of sale, lien search and inspection; have the approval before you bid.
Section 179 for Construction Equipment in 2026
A contractor buying $400,000 of equipment in 2026 can expense all of it under Section 179, worth roughly $80,000–$140,000 in federal tax depending on rate — often more than the first year of payments on the whole fleet addition. The 2026 Section 179 limit is $2,560,000 with 100% bonus depreciation above it; equipment must be placed in service by 31 December. See Section 179 and equipment financing.
Getting the Best Deal
- Pre-approve before auction season; a pre-approval letter lets you bid like a cash buyer.
- Match the term to the hours: a 6,000-hour excavator on 84 months is a decline; on 48 it is an approval.
- Finance attachments with the machine rather than on a card.
- Use seasonal or deferred payments if work is weather-dependent; most lenders offer 60–90-day deferrals.
- Keep a down payment ready for used deals — 10% shifts the rate meaningfully on older iron.
How RAN Funding Places Construction Equipment
Construction is one of the industries we fund most, and several lenders in our network specialize in heavy equipment, including used and auction units and B/C credit. One specialist, one application, and the lender pays the seller directly. Related: Construction business loans, equipment financing requirements, equipment financing rates.
Common Questions
Can I finance used construction equipment from an auction?
Yes. Most heavy-equipment lenders finance auction purchases against the auction invoice, with the machine inspected or condition-reported. Get pre-approved before the sale.
How much down payment do I need for an excavator?
Zero to 10% for established contractors with fair-or-better credit on newer machines; 10% to 20% on older used units, auction purchases or B/C credit.
Can a new contractor get equipment financing?
Yes, through start-up programs that rely on trade experience, a down payment of 15% to 25%, the machine’s value and often a signed contract or backlog.
What term can I get on construction equipment?
36 to 84 months, with the term tied to the machine’s age and hours. Newer machines get the longest terms.
Sources
- Equipment loan rates by industry 2026 — Crestmont Capital
- Equipment loan rates in 2026 — Equipment Financing HQ
- Section 179 deduction guide 2026 — Block Advisors
See What You Qualify For
One application, about five minutes, soft pull only. A funding specialist tells you up front whether SBA is realistic for your file — and which faster products fit if it is not.
More on Equipment Financing