
Industry · Food trucks and catering
Food Truck and Catering Business Loans: Trucks, Equipment, Event Deposits and Working Capital
Food trucks and caterers borrow for a second truck or trailer, a commissary kitchen, equipment that breaks mid-season, and the cash it takes to staff and stock a large event before the client pays the balance. The businesses are mobile, card-heavy and seasonal, which puts them in the sweet spot of equipment lenders and revenue-based funders and outside most banks’ comfort zone. This guide covers the options for operating food trucks and caterers in October 2026, costs with Prime at 7.00%, and how to qualify from a year in business (sometimes six months).
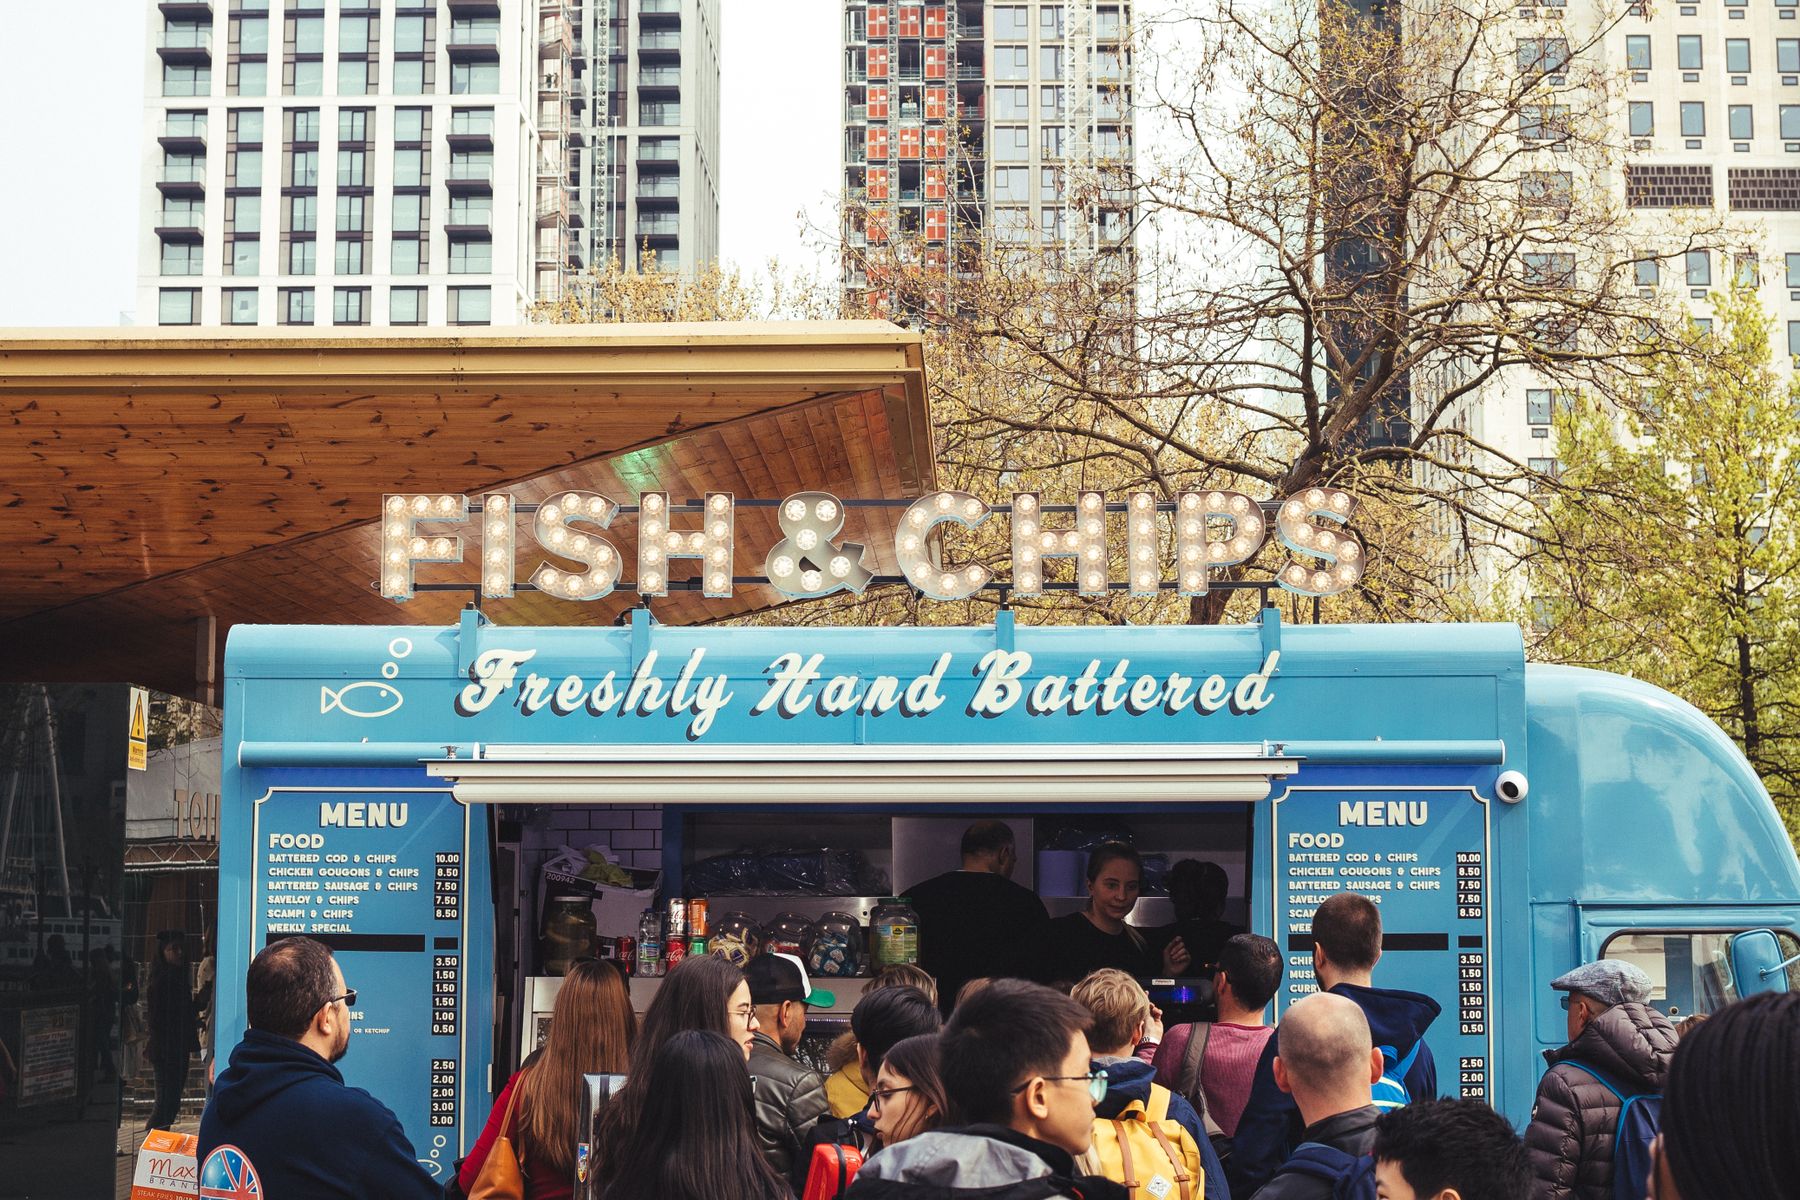
Can a Food Truck or Catering Business Get a Loan?
Yes. An operating food truck or catering company with a year or more of deposits (sometimes six months), $20,000 or more a month and owner credit from about 500 qualifies for revenue-based financing; a titled truck or trailer and commercial kitchen equipment qualify for equipment financing from 550 to 600 credit, with the vehicle as collateral, from $10,000 to about $250,000; from 600 credit and $20,000 a month, online lines of credit and term loans cover event staffing, inventory and marketing; from 680 and two years, a bank or SBA loan can fund a commissary or a fleet. The second truck is the most common request ($50,000 to $150,000 financed over three to five years); the second most common is working capital for the weeks between an event deposit and the final payment.
What Food Trucks and Caterers Borrow For
Needs come in two kinds: equipment that lasts years and cash gaps that last weeks.
| Need | Typical amount | Best-fit product | Why |
|---|---|---|---|
| Second truck, trailer or build-out | $50K – $150K | Equipment financing | Titled vehicle is the collateral; 3 – 5 year terms |
| Generator, refrigeration, cooking line, POS | $10K – $60K | Equipment financing | Funds in 2 – 7 days; vendor paid directly |
| Staffing and food for a large event before final payment | $10K – $50K | Line of credit or revenue-based financing | Short gap; repaid when the client pays |
| Commissary kitchen lease, permits, commercial insurance | $15K – $75K | Term loan | Fixed monthly payment |
| Off-season payroll and repairs | $10K – $40K | Line of credit | Draw only in the slow months |
Business Funding Products That Fit Food Trucks and Caterers
Equipment financing is the cheapest money most food businesses can get; use it for anything with a title or a serial number and keep unsecured borrowing for the short gaps.
| Product | Amounts | Cost at Prime 7.00% | Minimums | Funds in |
|---|---|---|---|---|
| Business line of credit | $10K – $250K online; more secured | 1.5% – 3% per draw (online); Prime + 1 to 4 bank | 6 mo, 600+, $20K/mo | 1 – 3 days |
| Term loan | $20K – $500K | 10% – 36% APR online; 7% – 11% bank | 12 mo, 600+, $20K/mo | 2 – 5 days |
| Revenue-based financing | $10K – $1M | Factor 1.15 – 1.45 | 6 mo, 500+, $20K/mo | 24 – 48 h |
| Equipment financing | $10K – $5M | 9.9% – 24% (6% – 12% bank) | 6 – 12 mo, 550 – 600+ | 2 – 7 days |
| Invoice factoring / A/R line | $20K – $5M | 1% – 4% per 30 days | B2B invoices, creditworthy customers | 3 – 7 days |
| SBA 7(a) | $50K – $5M | 10.00% – 13.50% | 2 yrs, 680+, no open advances | 30 – 60 days |
Current ranges by product and lender are in business loan interest rates; what each product requires is in business loan requirements.
How Lenders Read Food Truck and Catering Files
- Deposits from card readers and event clients are the revenue record; deposit cash sales too, or they do not exist to the lender.
- The truck is collateral only if it is titled and insured in the business’s name; a personally titled truck still works but changes the structure.
- Seasonality is normal; show twelve months so winter is read against festival season.
- Event contracts and deposits document receivables; a calendar of booked events helps a working-capital request.
- Permits and health inspections in good standing are checked by banks and SBA lenders, rarely by online funders.
Share of applicants fully approved, by product (Federal Reserve, 2026)
81% of applicants were approved for at least part of the request. Source: Federal Reserve Banks, 2026 Report on Employer Firms.
What $50,000 Costs Food Trucks and Caterers
| Option | Pricing | Term | Payment | Total cost |
|---|---|---|---|---|
| Bank line of credit | 9% interest-only | 90 days drawn | $375/month | $1,110 |
| Online line of credit | 2.5% per draw | 12 months | ~$985/week | $1,250 |
| Online term loan | 24% APR + 5% origination | 18 months | $3,500/month | $13,040 |
| Revenue-based financing | Factor 1.22 | 8 months | ~$350/business day | $11,000 |
| Equipment financing | 12% | 4 years | $1,317/month | $13,200 |
Total cost of $50,000, by option
Illustrative at October 2026 pricing. Compare total payback against the margin the money produces, not the rate alone.
Model your own numbers in the payment calculator and the qualification estimator.
How RAN Funding Places Food Truck and Catering Deals
Food truck and catering files go to equipment lenders that finance titled trucks and kitchen build-outs, and to revenue-based and line-of-credit funders for the event gaps. One application, the truck quote and three months of statements, and you see the approvals side by side.
- Apply once with a soft pull and the last three months of business bank statements (four in NY, CA or VA).
- A specialist reads the file the same day and presents it to the best-matched funders in our network for the best deal.
- You see the approvals side by side with total payback, payment and term, and decide.
- Funding in 24 hours to 5 days on most products; SBA in 30 to 60 days.
¿Prefiere español? Lea esta guía en español.
Common Questions
Can I finance a used food truck?
Yes. Most equipment lenders finance used trucks and trailers up to about ten years old, including private-party purchases, with a title, an inspection and sometimes 10% down.
How much can a food truck borrow?
Equipment loans cover up to 100% of the truck or equipment cost; working-capital products size at one to one and a half times monthly deposits, so a truck depositing $25,000 a month usually sees $25,000 to $37,500.
Do I need a commissary lease to get a loan?
Not for equipment financing or revenue-based products. Banks and SBA lenders will ask for the lease and permits as part of the full package.
What credit score does a caterer need?
About 500 for revenue-based financing, 550 to 600 for equipment, 600 for online lines and term loans, 680 for banks and SBA.
Is RAN Funding a lender?
No. RAN Funding is a business financing broker. We present your application to the funders in our network that fit your profile and show you the approvals that come back; the funding partner sets the approval, amount, rate, fees and terms. RAN Funding is paid by the lender, not by you.
Sources
- 2026 Report on Employer Firms: Findings from the 2025 Small Business Credit Survey — Federal Reserve Banks
- H.15 Selected Interest Rates (bank prime loan rate 7.00%) — Board of Governors of the Federal Reserve System
See What You Qualify For
One application, about five minutes, soft pull only. A funding specialist tells you up front which products fit your file, what they cost and how fast each one funds.
More on Food Business Financing